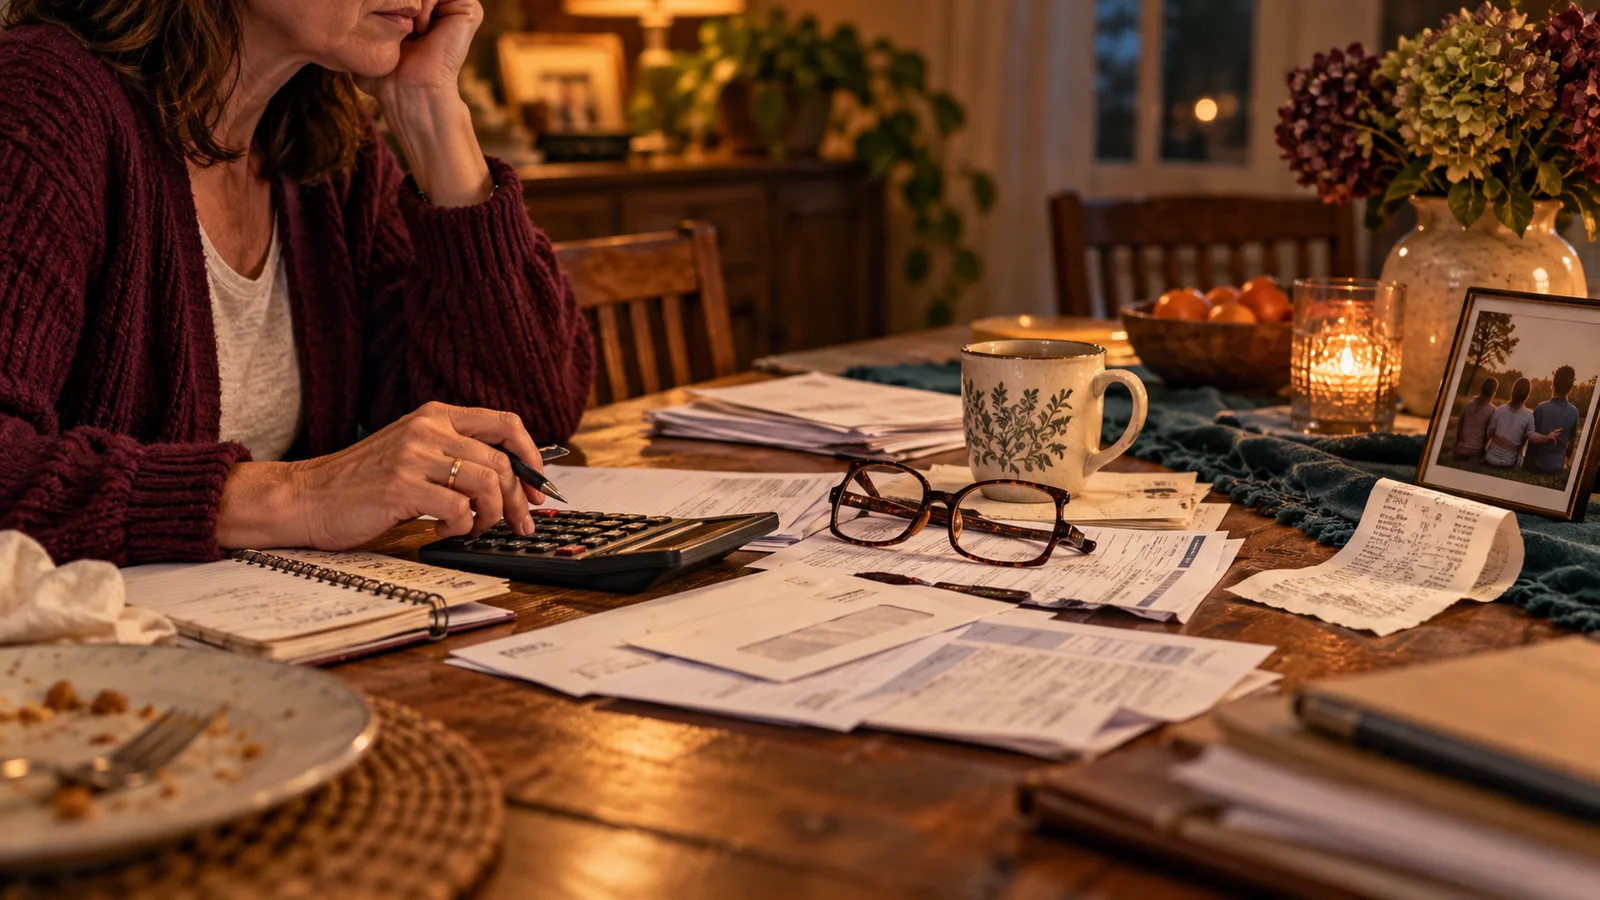
Retirement planning used to be an abstract civic virtue, like flossing or keeping the warranty paperwork. Then one day you are calculating whether your parent can afford help, your adult child needs a deposit and a cheerful online calculator asks whether you have saved eight times your salary.
You close the tab. The tab has not forgotten you.
Gen X arrived during the handoff
Many members of this generation entered work as employers were moving away from traditional pensions and toward employee-directed retirement accounts. The promise was flexibility and ownership. The practical result was that workers had to decide how much to save, where to invest and how to turn a pile of money into income—all while living through recessions, layoffs and long stretches of competing responsibilities.
The gap is especially visible for women. A 2025 Transamerica Center for Retirement Studies report found that 27% of Gen X women had less than $25,000 in total household retirement savings, excluding home equity. That is not a moral diagnosis. It is evidence that the standard story—start early, increase annually, never interrupt—did not match many actual lives.
You cannot shame a complicated financial life into becoming simple. You can make the next decision clearer.
Start with a map, not a verdict
Before deciding you are “behind,” find what exists. List workplace plans from current and former jobs, individual retirement accounts, pensions, Social Security estimates, cash savings, debts and major assets. Check fees, investment mix and beneficiary designations. Forgotten accounts and outdated beneficiaries are dull problems with potentially large consequences.
Then estimate the spending that would continue if you stopped working: housing, health care, food, transportation, insurance, taxes and support you expect to keep providing. A plan built on real spending is more useful than a universal multiple of salary.
Protect tomorrow from today’s emergencies
Helping family is often part of the plan, not an exception to it. But unlimited help can move risk from one generation to another. Decide what you can give without borrowing from retirement, taking high-interest debt or sacrificing essential insurance. “I can contribute this amount” is a complete sentence, even when the person asking is someone you love.
Caregiving deserves its own line. Time away from paid work can reduce wages, workplace contributions and future Social Security benefits. If siblings are involved, financial support and time should be discussed together; the person giving twenty hours a week is already contributing something valuable.
Choose the highest-value next move
For some people, the next move is capturing a full employer match. For others it is paying down expensive debt, building a modest emergency fund, consolidating old plans, revisiting investments or getting fiduciary advice. People closer to retirement may need a Social Security claiming strategy and a realistic plan for health coverage before Medicare eligibility.
Do not let an impressive dashboard substitute for understanding. Ask an adviser how they are paid, whether they act as a fiduciary, what the total fees are and what assumptions sit behind the projection. If the plan requires perfect markets and no family emergencies, it is fan fiction.
The reset can be small
One percentage point more into a workplace plan is not a solution to every shortfall. It is still an action. So is updating a beneficiary, locating an old account or scheduling one meeting. Momentum is not magic, but it is better than avoiding the tab for another year.
Editorial note: This is general educational information, not individualized financial, tax or legal advice. Rules and choices depend on your circumstances; consult qualified professionals where appropriate.
Sources
Transamerica Center for Retirement Studies: 25 Facts About Women’s Retirement Outlook
AARP: When the Math Stops Working
AARP: Social Security, women and caregivers